Austin & Larson Tax Resolution
Tax Lawyer In Handy Township, MI
Austin & Larson Tax Resolution represents Handy Township and Village of Fowlerville taxpayers against the IRS and the Michigan Department of Treasury, from our Brighton office on I-96. Tax attorneys, IRS Enrolled Agents and CPAs in one firm. Levies, wage garnishments, unfiled returns, Treasury assessments, balances you cannot pay. The first call costs nothing and it is with somebody who will work the file.
There is no tax attorney’s office in Handy Township
No office in ZIP 48836 lists tax law as a practice area. Tax controversy work for Livingston County gets done from Brighton, Howell and Lansing, and most of it never needs you in a room at all. Transcripts, powers of attorney and negotiations with the IRS and Treasury happen by mail, fax and phone regardless of which side of the county you sit on.
So distance is not the question worth asking. The question is whether whoever takes your file understands that you probably have 2 of them.
Tax Debt is Often
Intimidating
Frustrating
Confusing
Embarrassing
Stressful
… But it Doesn’t Have to Be
The Two-File Rule
Most Handy Township tax problems are not 1 debt. They are 2 separate files at 2 separate governments, and the rules diverge at almost every step. Closing one does not close the other. That is the single most expensive thing people get wrong.
File 1, the IRS
Federal collection runs on a 10-year statute from assessment. The IRS gives 30 days notice before most levies, and the options are the familiar ones: installment agreement, currently not collectible status, penalty abatement, Offer in Compromise on Form 656, audit reconsideration.
The Offer figures are worth seeing before anybody promises you one. In fiscal year 2025 the IRS received 38,797 Offers in Compromise and accepted 5,464 of them, for $98.1 million, per the IRS Data Book. Divide those 2 numbers and acceptance lands near 1 in 7. The counts come from different cohorts inside the same year, so the ratio is an approximation rather than a clean success rate.
An Offer is the right answer for a minority of the people who ask for one. For most of the rest it is an installment agreement, currently not collectible status, penalty relief, or getting the returns filed so the IRS stops estimating your income for you.
File 2, the Michigan Department of Treasury
Michigan is not the IRS with a different logo.
Treasury runs its own Offer in Compromise program under Public Act 240 of 2014. It uses the Form 5181 family, not federal Form 656, and versions predating 1 April 2025 are rejected outright. You send $100 or 20 percent of the offer, whichever is greater, it is applied to the debt, and it is not returned if the offer turns out to be ineligible.
There are 3 grounds: doubt as to collectability, doubt as to liability once your appeal rights have expired, or an accepted federal Offer. That last route reaches individual income tax, withholding tax and corporate income tax only. Sales tax cannot ride a federal acceptance into Michigan, though it can still be compromised on the collectability or liability grounds.
Treasury’s collection powers under Public Act 122 of 1941 do not mirror the IRS either. It records liens with the Livingston County Register of Deeds, and files them even where payment arrangements exist. It can levy wages or a bank account on at least 10 days notice and add $55 for each levy served. It intercepts income tax refunds, lottery winnings and vendor payments. It can assess an officer, member or partner personally as a responsible person under MCL 205.27a(5). It can ask the Liquor Control Commission not to renew a license. And under MCL 205.53 it can suspend a sales tax license after notice and a hearing, which is the power that closes a business on Grand River or Grand Avenue.
One thing it cannot do, whatever you have read. Michigan does not suspend a driver’s license over unpaid income tax. The statute people confuse it with, MCL 257.801c, suspends an operator’s license over a dishonored check written to the Secretary of State for a vehicle fee, and only once that claim has stood unpaid for at least 60 days. Name the right license and the risk gets manageable.
Why closing 1 file does not close the other
An accepted federal Offer does not settle your Michigan balance. A federal installment agreement does not stop a Treasury levy. A federal lien release does not clear a state lien from the Register of Deeds. Each government assesses separately, collects separately and settles separately, and each needs its own authorization: IRS Form 2848 and Michigan Form 151.
Any engagement we take covers both files, or we tell you at the start which one we are leaving alone.
If your parcel is farmed
The qualified agricultural exemption under MCL 211.7ee and 211.7dd exempts qualifying property from the local school operating levy, up to 18 mills. In Handy Township the homestead and non-homestead rates differ by exactly 18.0000 mills on all 4 lines above, which is the evidence that the full 18 is in play here.
There are 2 ways in. Either the parcel is classified agricultural on the roll, or more than 50 percent of the acreage is devoted to agricultural use as MCL 324.36101 defines it. Where the parcel is not classified agricultural, the owner files Form 2599 with the township assessor by 1 May.
There is no farm income requirement in this exemption. That test belongs to PA 116, a separate program, and even there it is tiered: none at all above 40 acres in qualifying use, $200 per year per cleared and tillable acre between 5 and 40 acres, and $2,000 in gross annual income for a specialty farm of 15 acres or more, per the Michigan Department of Agriculture and Rural Development. Enrolling in PA 116 does not hand you the qualified agricultural exemption, and unproductive ground can still qualify for it.
The trap is retail. Commercial storage, processing, distribution, marketing and shipping are carved out. In Blake’s Farm, Inc v Armada Township, a published Michigan Court of Appeals opinion issued 15 May 2025 under docket numbers 371397 and 371398, the court held that agritourism uses including a restaurant, a gift shop, a retail cider area, event space, parking lots and processing facilities are commercial and fall outside the exemption. It affirmed partial exemptions of 25.3 percent and 54 percent on the 2 parcels, and rejected the argument that the Right to Farm Act’s broader definition of a farm operation governs eligibility under the General Property Tax Act.
Worth reading before a farm stand goes up on the road frontage, not after.
Two mechanics to hold onto. Selling qualified agricultural property does not uncap its taxable value if the property stays qualified agricultural and the buyer files Form 3676 with both the assessor and the register of deeds. And when agricultural use stops, a rescission is due within 90 days or a penalty of $5 a day runs to a $200 cap, on top of the recapture tax.
What We Do | Tax Resolution
Offer In Compromise
Installment Agreements
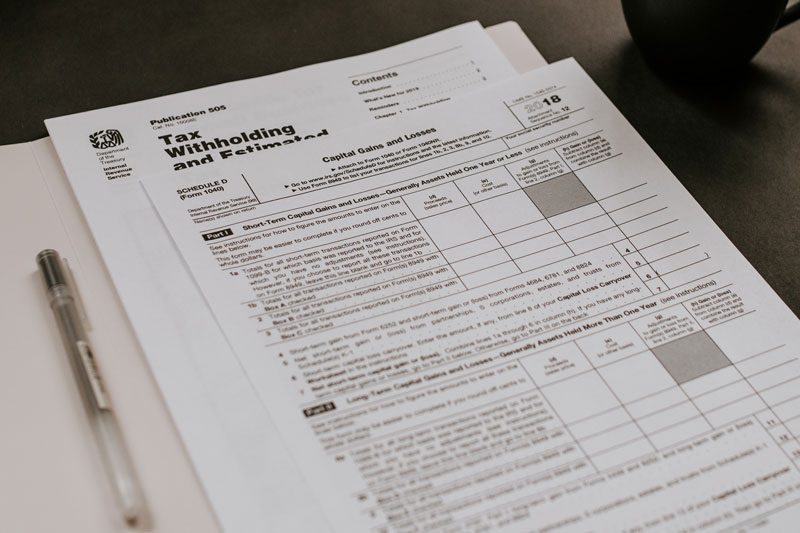
Non-Collectable Status
Compliance
Revenue Officer Representation
Levies & Wage Garnishments
Bankruptcy
Audit Representation
Tax Return Preparation
Handling tax resolution may feel daunting, but with our expert guidance, you'll experience relief knowing seasoned professionals are by your side. At Austin & Larson Tax Resolution, our experienced Michigan tax lawyers are dedicated to delivering the reassurance and help you deserve. Well-regarded for their expertise and in-depth understanding of Michigan State tax regulations, our proficient tax relief lawyers provide a full spectrum of services, from thorough consultations to exceptional legal advocacy, all focused on securing the most favorable resolution to your tax matters.
Learn From The Experts
Qualified Amended Return: Avoiding The 20% IRS Penalty
Written By: Michael Vale Reviewed By: Bridgette Austin, Esq., EA, Co-Founder and Tax Attorney Last Reviewed: October 18, 2026 A qualified amended return is the one move that erases the IRS accuracy-related penalty instead of arguing about it later. File it before the...
Accountant Client Privilege In Michigan: What It Covers And Where It Fails
Written By: Michael Vale Reviewed By: Bridgette Austin, Esq., EA, Co-Founder and Tax Attorney Last Reviewed: October 11, 2026 Michigan gives your accountant a real privilege. Federal law gives you almost none. Under Michigan's own statute, a CPA can't be made to turn...
IRS Information Document Request: What The IRS Can Ask
Written By: Michael Vale Reviewed By: Bridgette Austin, Esq., EA, Co-Founder and Tax Attorney Last Reviewed: October 4, 2026 An IRS information document request is a written list of records an examiner wants from you, with a date to hand them over. It arrives on Form...
What we handle, and what we route elsewhere
Austin & Larson handles tax debt: IRS and State of Michigan. Everything above about millage lines, assessments and exemptions is on this page because a Handy Township owner should be able to find it somewhere. It is not a service we sell.
If your problem is the number on your assessment notice, your Principal Residence Exemption or your agricultural exemption, the route runs through the township first and the Michigan Tax Tribunal second.
Handy Township hall sits at 135 N. Grand Avenue, Fowlerville, and the office opens Monday, Wednesday and Thursday on (517) 223-3228. Barry Wauldron is the township assessor. Under MCL 211.29 and 211.30 the Board of Review organizes on the Tuesday after the first Monday in March and hears protests from the second Monday, which falls on 2 and 8 March in 2027. The township does not publish those dates far ahead, so February is the month to call.
The Michigan Tax Tribunal comes after that, and its deadlines are jurisdictional. 31 May for commercial, industrial and developmental real property and for commercial, industrial and utility personal property. 30 June for a classification appeal under MCL 211.34c(6). 31 July for residential, agricultural and timber-cutover real property and agricultural personal property. 35 days from a final determination for everything else, a Principal Residence Exemption denial included. The Tribunal states on its own site that it cannot extend the time for filing a petition. For a house or a farm, protesting to the March Board of Review first is a prerequisite; skip it and the Tribunal has no jurisdiction over your valuation appeal that year.
One more honest answer. If your income is low enough to qualify, the Michigan State University College of Law Low-Income Taxpayer Clinic represents taxpayers in federal controversy matters at no charge. For some people that is a better answer than hiring anybody, and we would rather say it here than after a consultation.
Looking For A Fresh Start in Michigan?
We Are Here To Help!
Should the weight of tax debt be pressing down on you, we urge you to connect with us to avail of a no-cost
consultation. Our objective revolves around untangling tax debt complexities for clients entangled in an array of
tax-related dilemmas. It would bring us immense satisfaction to furnish you with solutions to your inquiries and aid
you in swiftly settling your tax debt matters.
Our Process | Simple, Fast & Stress Free
Step 1: Initial Contact
During your first call to our office, we will ask you a brief
background of your current tax situation and determine the
most convenient office location for your free initial
consultation.
Step 2: Free Consultation
We will meet with you to review and discuss your individual
facts and circumstances to create a customized tax relief plan
for your situation and the next steps to take to resolve your tax
situation.
Step 3: Begin Resolving Debt
Once we have decided to move forward, we will immediately begin working with the IRS on your behalf to resolve your
case as quickly as possible. We will also provide advice and the steps you need to take to ensure you do not acquire
any additional debt while we work to settle your case. From the moment you retain our firm, we will be your voice with
the IRS and the point of contact for all taxing entities.
Step 4: Monitor Case Status
Some tax debt cases can be resolved quickly, while others may
have quite a bit of back and forth contact with the IRS to reach
full resolution. We will regularly monitor your case and keep
you in the loop along the way so you are never left in the dark.
Step 5: Tax Freedom!
It is our goal not only to resolve your current tax debt but also
to make sure that you don't have any further tax problems.
After we have reached resolution with your case, you will be
fully equipped with best practices to avoid future tax issues of
any kind.
Frequently Asked Questions
Is there a tax attorney in Handy Township, or am I driving to Brighton?
No office in Handy Township or the Village of Fowlerville lists tax law as a practice area. For tax controversy you are looking at Brighton, Howell or Lansing. Our Brighton office is east on I-96 from Exit 129, and most of our clients never come in, because representation before the IRS and Treasury runs on transcripts, forms and phone calls rather than meetings.
The IRS accepted my Offer in Compromise. Is Michigan finished too?
No. Michigan runs a separate program under Public Act 240 of 2014 with its own forms. An accepted federal Offer is 1 of 3 grounds for a Michigan Offer, and that route reaches individual income tax, withholding tax and corporate income tax only. Sales tax has to go in on collectability or liability grounds instead. You still file, Treasury still decides, and the payment sent with the offer is not refundable if you turn out to be ineligible.
Do I qualify for the agricultural exemption, and will a retail barn cost me it?
You qualify if the parcel is classified agricultural on the roll, or if more than 50 percent of the acreage is in agricultural use as MCL 324.36101 defines it. Where it is not classified agricultural, Form 2599 goes to the assessor by 1 May. Retail can cost you part of it. In Blake’s Farm, Inc v Armada Township the Court of Appeals upheld partial exemptions of 25.3 and 54 percent where restaurant, gift shop, retail and event uses sat on the parcels. Get the footprint looked at before building.
Will Michigan take my driver’s license over unpaid taxes?
No. Treasury’s collection powers do not include driver’s license suspension for unpaid income tax. MCL 257.801c, which people confuse it with, suspends an operator’s license over a dishonored check written to the Secretary of State for a vehicle fee, and only after the claim has stood unpaid 60 days. What Treasury can take from a business is the sales tax license, suspended after notice and a hearing under MCL 205.53, and it can ask the Liquor Control Commission to refuse a renewal.
March Board of Review or 31 July Tribunal? Which clock am I on?
Both, in that order, for a house or a farm. Protest to the March Board of Review first or the Tribunal has no jurisdiction over your valuation appeal, then petition by 31 July. Commercial, industrial and developmental real property can skip the board and file by 31 May. A classification fight runs to 30 June. A Principal Residence Exemption denial is 35 days from the determination. The Tribunal cannot extend any of them.
What is the difference between a tax attorney, a CPA and an enrolled agent?
All 3 can represent you before the IRS. An enrolled agent or a CPA is usually the better answer for returns, bookkeeping and a basic payment plan. An attorney brings privilege, which matters when the facts are bad, and is who you want when a notice of deficiency is on the desk, when the file could turn criminal, or when bankruptcy sits alongside the tax question. We hold all 3 credentials in one firm, so the answer to who should handle your file does not depend on who you happened to call.
Talk to a tax attorney about your Handy Township file
The consultation is free, and the first thing we do is tell you whether the problem is ours. If it belongs at the township or the Tribunal, you hear that on the first call.
Weekdays 8am-6pm
Brighton, Saginaw, Lansing, and Jackson, MI
Call Us Today or Fill Out The Form
Fill out the form below or give us a call today to speak with one of our tax experts!